How to Create a Personal Savings Plan Step by Step
Saving money becomes easier when you have a clear plan. Instead of saving whatever remains at the end of the month, you decide how much to save, what the money is for, and when you want to reach your goal.
A personal savings plan does not need to be complicated. With the right steps, you can start with a small amount, build useful habits, and make steady progress toward emergencies, major purchases, family responsibilities, and long-term goals.
Key Takeaways
Start by understanding your income, expenses, debt, and current savings.
Set clear savings goals with specific amounts and deadlines.
Build a starter emergency fund before focusing on larger goals.
Divide large goals into smaller monthly contributions.
Automate your savings on payday.
Keep money for different goals in separate accounts or categories.
Include irregular expenses in your plan.
Save part of every bonus, refund, gift, or extra payment.
Review your plan every month and update it when your life changes.
Choose a realistic amount so you can continue saving consistently.
What Is a Personal Savings Plan?
A personal savings plan is a simple system for deciding how much money you will save, where you will keep it, and what you want to achieve with it.
A savings plan may include money for:
Emergency expenses
Annual bills
Education
A vehicle
A home
Travel
A wedding
Medical costs
Business plans
Retirement
Family support
Your plan can include short-term and long-term goals. The purpose is to make saving a regular part of your financial life instead of something you do only when extra money appears.
Why Do You Need a Savings Plan?
Without a plan, saving often becomes inconsistent. You may save during one month, spend everything the next month, and then start again later.
A savings plan helps you:
Prepare for unexpected expenses
Avoid unnecessary borrowing
Pay for large purchases without using expensive debt
Build financial confidence
Reach goals more quickly
Manage irregular bills
Reduce financial stress
Create better spending habits
Saving also gives your income a clear purpose. Instead of asking whether you can afford something today, you can consider how the purchase affects your future goal.
Step 1: Calculate Your Monthly Income
Start by finding out how much money you can actually use each month.
Use your take-home income after taxes, deductions, insurance, and other automatic payments.
Your income may include:
Salary
Freelance payments
Business income
Part-time work
Rental income
Pension
Interest
Regular family support
If your income changes every month, use a conservative estimate. Base your essential plan on the lowest amount you reasonably expect to receive.
For example, if your monthly income is usually between ₹40,000 and ₹60,000, create your basic plan around ₹40,000. Treat income above that amount as extra money for savings, debt, or planned expenses.
Step 2: Track Your Current Spending
Before deciding how much to save, track your spending for at least 30 days.
Record:
Rent or home payments
Groceries
Utilities
Transport
Healthcare
Debt payments
Shopping
Eating out
Entertainment
Subscriptions
Personal care
Family support
Cash expenses
Use a notebook, phone note, spreadsheet, or budgeting app. Choose a system that is easy enough to use every day.
Do not skip small purchases. A few small payments may explain why your balance disappears before payday.
Step 3: Calculate Your Essential Expenses
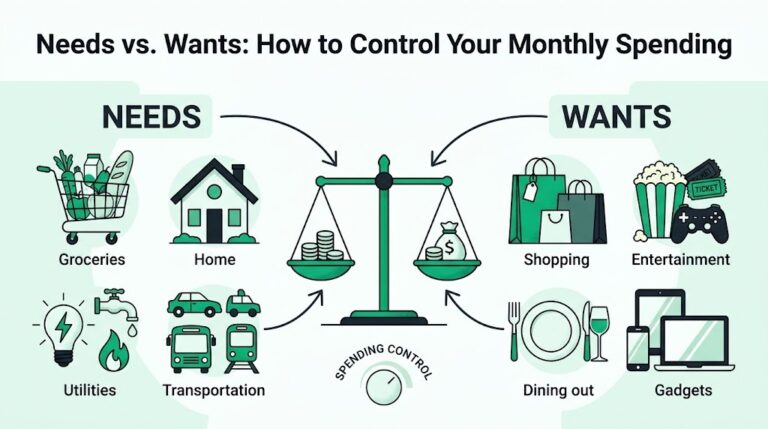
Separate your expenses into essential and optional categories.
Essential expenses may include:
Housing
Basic food
Electricity and water
Necessary transport
Medicines
Insurance
School fees
Minimum debt payments
Childcare
Important family responsibilities
Optional expenses may include:
Restaurant meals
Entertainment
Premium subscriptions
Shopping
Hobbies
Luxury products
Frequent taxi rides
Unplanned travel
Subtract your essential expenses from your income.
For example:
Monthly income: ₹50,000
Essential expenses: ₹32,000
Amount available for savings, debt, wants, and irregular costs: ₹18,000
This does not mean you can save all ₹18,000. Some of it may be needed for personal spending and future bills.
Step 4: List Your Current Savings and Debt
Write down the savings you already have.
Include:
Bank savings
Cash savings
Fixed deposits
Emergency fund
Goal-based savings
Retirement savings
Then list your debts:
Credit cards
Personal loans
Vehicle loans
Education loans
Family loans
Buy-now-pay-later balances
Record the balance, minimum payment, interest rate, and due date for each debt.
This information helps you choose the right order for your savings plan.
Step 5: Decide What You Are Saving For
Saving without a purpose can feel difficult. Give each savings goal a clear name.
Possible goals include:
Starter emergency fund
Medical fund
Vehicle fund
Education fund
Home deposit
Travel fund
Annual bills
Business fund
Retirement fund
Debt repayment
Ask yourself:
What financial problem do I want to solve?
What expense do I want to prepare for?
What future purchase matters most?
What would make my life more stable?
Which goal is most urgent?
Your answers will help you decide which goal should come first.
Step 6: Separate Goals by Time
Organize your goals into three time periods.
Short-Term Savings Goals
These usually take less than one year.
Examples include:
Saving for insurance
Paying annual fees
Creating a small emergency fund
Buying a necessary appliance
Paying for a short trip
Covering school expenses
Medium-Term Savings Goals
These may take one to five years.
Examples include:
Buying a vehicle
Saving for education
Starting a small business
Building a larger emergency fund
Planning a wedding
Saving for a home deposit
Long-Term Savings Goals
These usually take more than five years.
Examples include:
Retirement
Buying a home
Supporting children’s education
Long-term investments
Becoming debt-free
Building financial independence
This structure helps you choose suitable places to keep the money and decide how much attention each goal needs.
Step 7: Build a Starter Emergency Fund
Your first savings goal should usually be a small emergency fund.
You can start with:
₹5,000
₹10,000
One week of essential expenses
The cost of your most common emergency
This money can help with:
Urgent medical needs
Essential repairs
Emergency travel
Temporary income loss
Necessary family support
Once you reach your starter target, continue building toward one month of essential expenses. Over time, you may aim for three to six months.
A starter emergency fund gives you protection while you work on larger financial goals.
Step 8: Set a Specific Amount and Deadline
A savings goal becomes easier to follow when you know the exact amount and date.
For example:
Goal: Save for a vehicle
Total needed: ₹240,000
Current savings: ₹40,000
Amount remaining: ₹200,000
Deadline: 24 months
Your monthly target would be:
₹200,000 ÷ 24 = about ₹8,333 per month
If that amount does not fit your budget, you can:
Extend the deadline
Lower the goal amount
Increase your income
Reduce optional spending
Save part of bonuses
Choose a lower-cost option
A realistic deadline is better than an aggressive target you cannot maintain.
Step 9: Create Separate Savings Categories
Keeping all your savings in one general account can make it difficult to know what the money is for.
Create clear categories such as:
Emergency fund
Annual bills
Medical costs
Vehicle
Education
Travel
Home
Retirement
You can use separate bank accounts, digital savings spaces, envelopes, or a spreadsheet.
The goal is to prevent money saved for one purpose from being spent on another.
Step 10: Choose a Monthly Savings Amount
Your monthly savings amount should fit your actual budget.
You may start with:
₹500
₹1,000
₹2,000
5% of your income
10% of your income
A specific amount linked to a goal
If you earn ₹40,000 per month, saving ₹2,000 may be a good starting point. If you earn ₹80,000 and have lower expenses, you may be able to save more.
Do not choose an amount that forces you to borrow before the month ends. A smaller amount saved consistently is better than a large amount saved only once.
Step 11: Pay Yourself First
Save before you begin regular spending.
When your income arrives:
Transfer money to your savings goals.
Pay essential bills.
Make debt payments.
Use the remaining money for groceries, transport, and flexible spending.
If you wait until the end of the month, your savings may depend on whatever remains. Paying yourself first gives savings a protected place in your budget.
Step 12: Automate Your Savings
Automatic transfers can make your personal savings plan easier to follow.
Set up an automatic transfer for payday or the day after your income arrives.
You can automate:
Emergency savings
Retirement contributions
Annual bill savings
Education savings
Vehicle savings
Home deposit savings
If your income changes each month, transfer a percentage instead of a fixed amount.
For example, you could save 5% of every payment you receive. During higher-income months, your savings will increase automatically.
Step 13: Create a Budget for Your Savings Plan
Your savings plan should appear in your monthly budget.
For example, if your monthly income is ₹60,000, your budget may look like this:
Essential expenses: ₹38,000
Emergency fund: ₹5,000
Debt repayment: ₹4,000
Annual bills fund: ₹3,000
Long-term savings: ₹3,000
Personal spending: ₹4,000
Flexible reserve: ₹3,000
Total planned amount: ₹60,000
This plan gives your savings a fixed place instead of treating them as an afterthought.
Step 14: Reduce Spending Without Making Life Miserable
You do not need to remove everything enjoyable to save money.
Look for expenses that provide low value, such as:
Unused subscriptions
Frequent delivery fees
Impulse shopping
Unplanned online purchases
Expensive convenience services
Repeated snacks and drinks
Unused memberships
Choose one or two categories to reduce first.
For example, if you spend ₹4,000 per month on food delivery, reducing that to ₹2,500 creates ₹1,500 for your savings plan without eliminating restaurants completely.
Step 15: Use Extra Income for Your Goals
Extra money can help you reach savings goals faster.
Consider saving part of:
Work bonuses
Gifts
Refunds
Freelance income
Overtime pay
Business profits
Items sold from your home
Salary increases
You do not need to save all extra income. One possible split is:
50% toward your main savings goal
30% toward debt or emergency savings
20% for personal use
Choose a split that supports your current priorities.
Step 16: Plan for Irregular Expenses
Not every important expense appears monthly.
Examples include:
Vehicle repairs
Insurance renewals
School fees
Medical tests
Festival spending
Gifts
Travel
Home maintenance
Professional fees
Estimate the yearly cost and divide it by 12.
If your annual insurance costs ₹24,000, save ₹2,000 each month. When the payment is due, you will already have the money available.
This prevents predictable bills from becoming emergencies.
Step 17: Use Sinking Funds
A sinking fund is money saved gradually for a known future expense.
You can create sinking funds for:
Annual fees
Holidays
Repairs
Gifts
Education
Medical care
Vehicle maintenance
Technology replacement
Keep these funds separate from your emergency fund. A planned vacation should not use the money reserved for a medical emergency.
Step 18: Manage Debt Alongside Savings
Debt can make it harder to save, especially when interest rates are high.
Continue making minimum payments on all debts. Then decide whether extra money should go toward debt or savings.
A practical approach is:
Build a small emergency fund.
Pay minimums on every debt.
Focus extra payments on high-interest debt.
Continue a small regular savings contribution.
Increase savings after expensive debt is under control.
The exact balance depends on your income, interest rates, job stability, and responsibilities.
Step 19: Protect Your Savings From Everyday Spending
Keep savings away from your everyday spending account when possible.
A separate account can help you:
See your progress
Avoid accidental spending
Automate contributions
Stay focused on the goal
Protect emergency money
Use account names such as “Emergency Fund,” “Education,” or “Vehicle” to remind yourself why the money is there.
Step 20: Choose Safe Places for Short-Term Savings
Money needed soon should be kept somewhere safe and accessible.
Short-term savings may be needed for:
Emergency expenses
Annual bills
A purchase within the next year
Medical costs
A planned event
Avoid putting money needed soon into an option that may lose value or be difficult to access quickly.
Long-term savings may have different options, but the right choice depends on your goals, risk tolerance, country, tax rules, and financial situation.
Step 21: Review Your Progress Monthly
Set aside time once a month to review your savings plan.
Ask:
Did I save the planned amount?
Which goal grew the most?
Did I use savings for an unexpected expense?
Did my income change?
Did any expense increase?
Is my deadline still realistic?
Should I adjust the monthly contribution?
A monthly review helps you correct problems early.
Step 22: Increase Savings Gradually
You do not need to double your savings immediately.
Try increasing your contribution when:
Your salary increases
You pay off a loan
A subscription is canceled
Your rent decreases
Your household expenses fall
You receive extra income
Even increasing your savings by ₹500 per month can create meaningful progress over time.
Step 23: Use the 24-Hour Purchase Rule
Before buying a non-essential item, wait 24 hours.
For larger purchases, wait a week.
During the waiting period, ask:
Is this included in my budget?
Do I already own something similar?
Can I pay without using debt?
Will I use it regularly?
Does buying it delay an important goal?
The waiting period helps separate real priorities from temporary excitement.
Step 24: Track Your Savings Rate
Your savings rate is the percentage of your income that goes toward savings and certain financial goals.
For example, if you earn ₹50,000 and save ₹5,000, your savings rate is 10%.
You do not need to chase a specific number. Tracking the rate helps you measure progress when your income changes.
If your income increases and your savings rate stays the same, the amount you save will still increase.
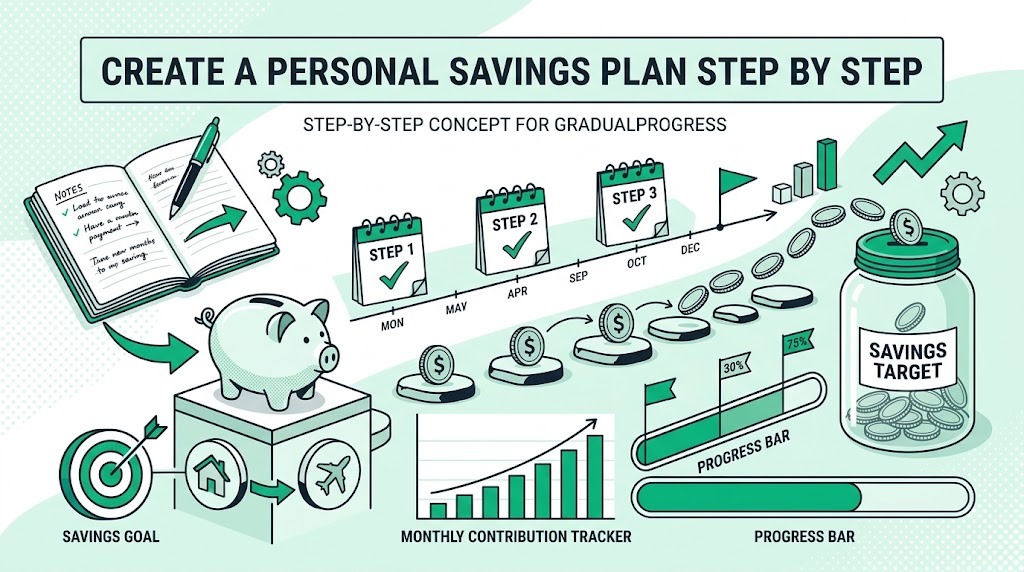
Step 25: Make Your Savings Progress Visible
Savings can feel slow when the goal is large. Use a visual tracker to make progress easier to see.
You can use:
A savings chart
A phone note
A spreadsheet
A progress bar
A monthly checklist
A printed goal sheet
Mark each milestone, such as:
First ₹5,000
First ₹10,000
25% of the goal
Halfway point
75% completed
Final target
Visible progress can make it easier to continue.
Example Personal Savings Plan
Imagine your monthly take-home income is ₹55,000.
Your essential costs are:
Rent: ₹15,000
Groceries: ₹7,000
Utilities: ₹3,000
Transport: ₹3,000
Phone and internet: ₹1,500
Healthcare: ₹1,500
Minimum debt payments: ₹4,000
Total essential expenses: ₹35,000
You have ₹20,000 available for savings, goals, irregular expenses, and personal spending.
Your plan could be:
Emergency fund: ₹6,000
High-interest debt: ₹4,000
Annual bills fund: ₹3,000
Long-term savings: ₹3,000
Personal spending: ₹4,000
Total: ₹20,000
After the emergency fund reaches its target, you can redirect the ₹6,000 toward debt repayment, a home goal, education, or another priority.
What If You Cannot Save Right Now?
Sometimes your income is already fully used by essential expenses. In that situation, do not create an unrealistic savings target.
Start by:
Tracking all expenses
Reducing avoidable fees
Reviewing subscriptions
Comparing bills
Planning meals
Looking for additional income
Selling unused items
Asking whether debt payments can be adjusted
Saving a very small amount when possible
Even ₹100 or ₹500 can help you begin the habit. If your expenses are higher than your income, focus first on creating a balanced monthly plan.
Common Savings Plan Mistakes
Saving Without a Specific Goal
A general savings balance may be easier to spend. Give your money a name and purpose.
Choosing an Impossible Monthly Amount
A large target is not useful if it forces you to borrow later. Make the amount realistic.
Keeping All Savings in One Place
Separate categories can help you avoid using emergency money for a planned purchase.
Forgetting Annual Costs
Predictable yearly expenses should be part of your monthly plan.
Using Emergency Savings for Wants
Keep a separate personal spending category for entertainment, shopping, and optional purchases.
Stopping After One Bad Month
A difficult month does not erase your progress. Adjust the plan and continue.
Never Increasing Your Savings
Review your contribution when your income rises or your debt decreases.
A Step-by-Step Savings Plan You Can Start Today
Follow these steps:
Write down your monthly take-home income.
List your essential expenses.
Track all spending for 30 days.
Choose your first savings goal.
Set a realistic amount and deadline.
Open a separate savings space.
Automate the monthly transfer.
Reduce one low-value expense.
Review your progress every month.
Increase the amount when your finances improve.
You do not need to complete every long-term goal immediately. Start with one useful goal and create a system you can repeat.
Frequently Asked Questions
How much should I save each month?
Save an amount that fits your income and expenses. You can start with ₹500, ₹1,000, or 5% of your monthly income.
The most important part is saving consistently without creating a shortage later in the month.
What should my first savings goal be?
A small emergency fund is a useful first goal. Start with ₹5,000, ₹10,000, or one week of essential expenses.
After that, you can focus on debt, annual bills, education, a vehicle, or another important goal.
Should I save money or pay off debt first?
Continue minimum payments on all debts and build a small emergency buffer. Then focus extra money on high-interest debt while maintaining a small regular savings contribution.
Once expensive debt is under control, increase your savings.
Where should I keep my savings?
Keep short-term and emergency savings in a safe, accessible place separate from your everyday spending account.
Long-term savings may use different options, depending on your goals, risk tolerance, and local financial rules.
How can I save with an irregular income?
Use your lowest expected monthly income to plan essential expenses. Save a percentage of every payment instead of relying on a fixed amount.
During high-income months, direct some extra money toward emergency savings, debt, or future goals.
What if I need to use my savings?
Use the money if the expense is a genuine emergency or the goal has arrived. Afterward, rebuild the amount through automatic transfers, reduced optional spending, or extra income.
Using savings for the right reason does not mean your plan failed.
How many savings goals should I have?
You can have several goals, but focus on one or three main priorities at a time. Too many goals may spread your money so thin that progress becomes difficult to see.
Give urgent goals priority and make smaller contributions to long-term goals when possible.
How often should I update my savings plan?
Review your progress every month and complete a deeper review once or twice a year.
Update the plan sooner if your income, rent, debt, health, family responsibilities, or major expenses change.
Is saving 10% of my income enough?
Saving 10% can be a useful starting point, but the right amount depends on your situation. Some people can save more, while others may need to start with less.
A sustainable contribution is better than a target you cannot continue.
How can I stay motivated while saving?
Give each goal a clear name, track your progress, and celebrate milestones without spending too much.
Remind yourself what the money will help you achieve. A visible reason makes saving easier than focusing only on the balance.